ICTSI reports higher earnings as new terminals drive container growth
International Container Terminal Services, Inc. (ICTSI) reported higher revenue and earnings for the first nine months of 2026, supported by newly integrated container terminals and stronger operating income across its international portfolio.
The Philippines-based terminal operator recorded revenue from port operations of US$2.90 billion, an increase of 24% from US$2.34 billion in the corresponding period of 2025. Net income attributable to equity holders rose by 20% to US$898.89 million, while EBITDA increased by 21% to US$1.87 billion.
Excluding a nonrecurring charge associated with the sale of Yantai International Container Terminal in China, recurring net income reached US$913.59 million, representing growth of 22%.
For the third quarter alone, ICTSI generated revenue of US$984.05 million, up 19% year on year, while net income attributable to equity holders increased by 15% to US$308.90 million.
New terminals account for much of throughput growth
ICTSI handled 12.11 million TEUs during the first nine months of 2026, an increase of 13% compared with 10.69 million TEUs in the same period last year.
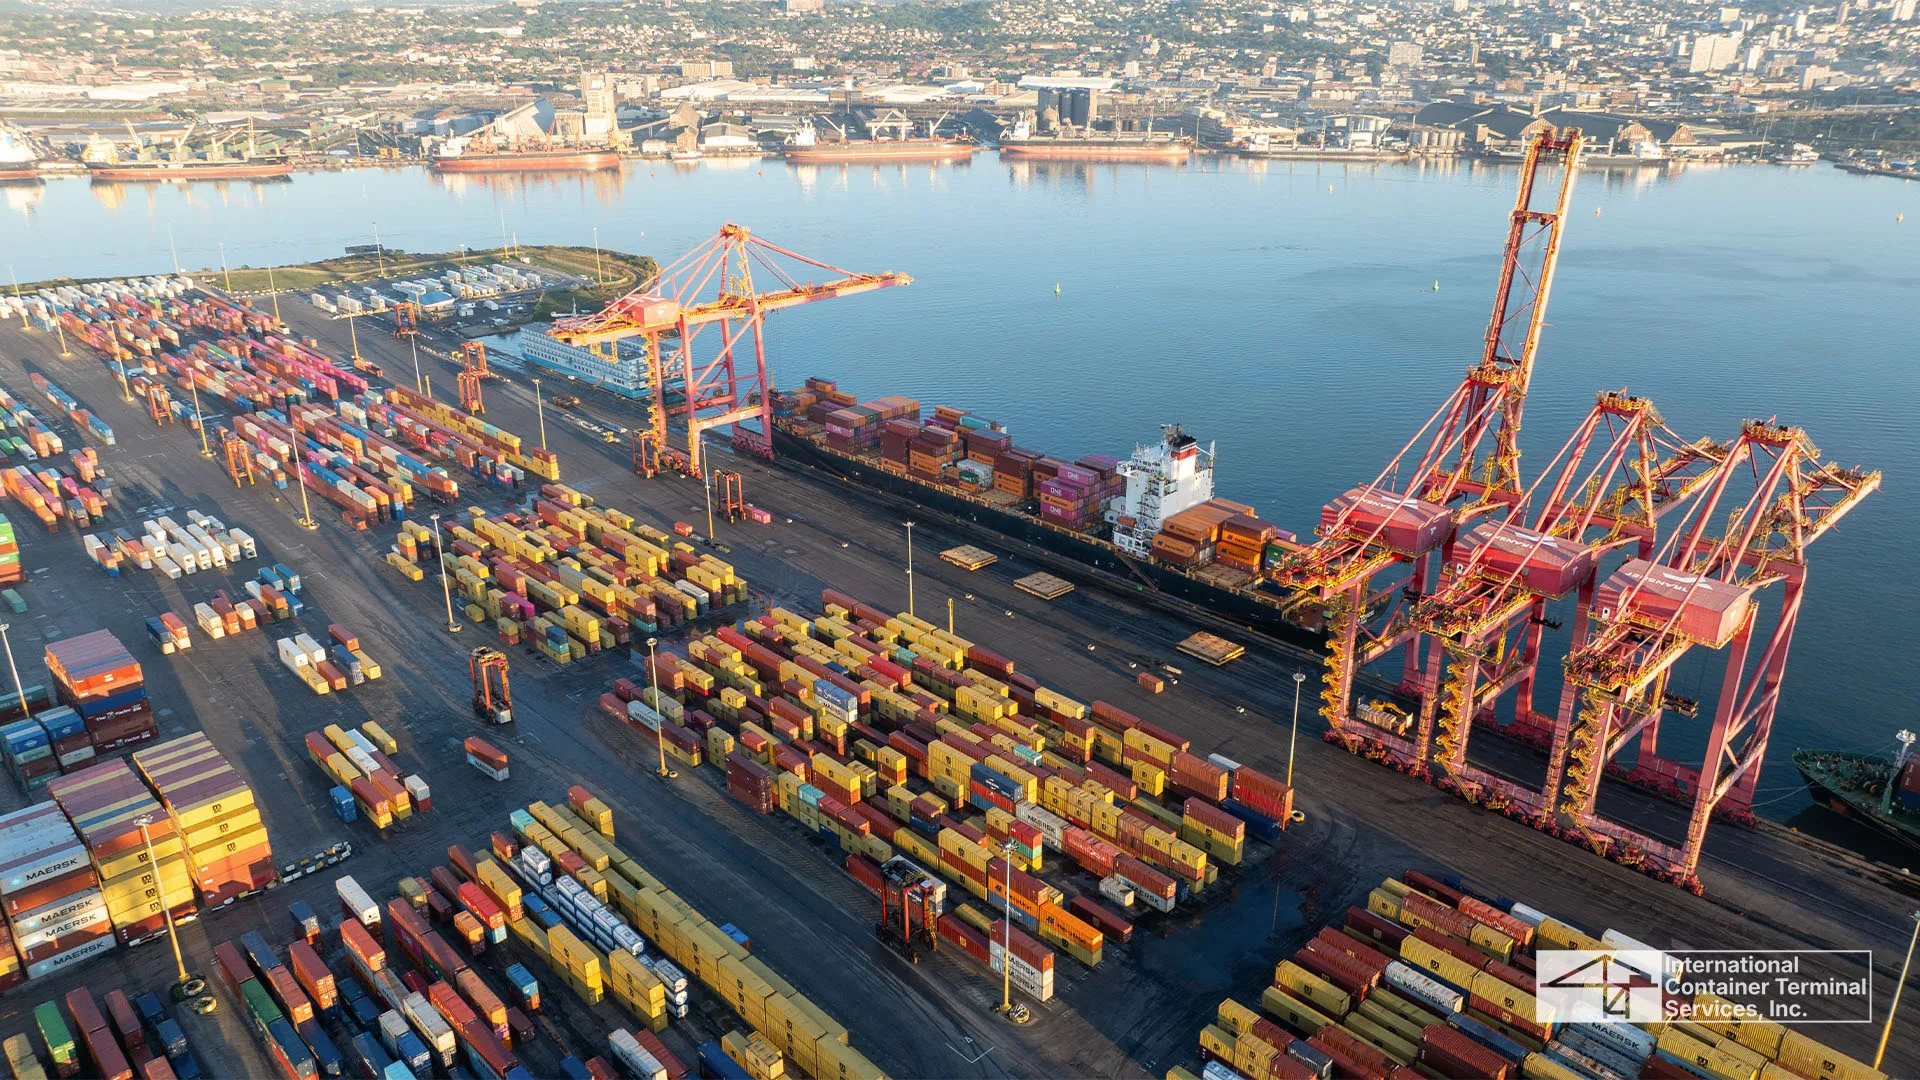
The growth was largely attributable to the addition of Durban Gateway Terminal in South Africa and Batu Ampar Container Terminal in Indonesia. Durban Gateway Terminal assumed operations at Durban Container Terminal Pier 2 in January 2026, while Batu Ampar began contributing to ICTSI’s consolidated results following its operational takeover in September 2025.
Improved trade activity in Asia and the Americas also supported volumes, although the company reported lower throughput at certain terminals in Europe, the Middle East and Africa.
Basra Gateway Terminal in Iraq was particularly affected by geopolitical conflict in the Middle East, while the disposal of Yantai International Container Terminal reduced the group’s consolidated volumes.
Excluding the contribution of Durban and Batu Ampar and the impact of the discontinued Yantai operation, ICTSI’s container throughput would have increased by only 0.1% year on year.
The adjusted figure indicates that expansion of the terminal portfolio accounted for most of the reported growth in consolidated container volumes.
Third-quarter throughput reached approximately four million TEUs, an increase of 8% compared with the corresponding period of 2025.
Revenue growth exceeds underlying volume expansion
ICTSI’s revenue performance reflected factors beyond container volume growth, including a more favourable cargo mix, higher ancillary service revenues and tariff adjustments at selected terminals.
Currency movements also influenced reported results, particularly the appreciation of the Mexican peso, Australian dollar and Brazilian real against the US dollar.
Excluding newly added and discontinued operations, consolidated gross revenue would have increased by 15%, despite the marginal growth in adjusted container throughput.
However, operating costs also increased significantly. Consolidated cash operating expenses rose by 37% to US$801.40 million, reflecting the contribution of new operations, higher activity-related expenses, increased fuel costs and salary adjustments.
The group’s EBITDA margin consequently declined from 66% to 64%, primarily due to the integration of newly acquired terminal operations. Excluding new and discontinued activities, ICTSI reported that its EBITDA margin would have improved slightly to above 66%.
Enrique K. Razon Jr., Chairman and President of ICTSI, said recently added terminals had contributed to the group’s performance, alongside continued revenue and earnings growth at existing operations.
The company remains focused on integrating these facilities and expanding capacity across its network.
Investment programme continues across global terminals
ICTSI reported capital expenditure of US$507.43 million during the first nine months of 2026, excluding capitalised borrowing costs.
The company maintains an estimated full-year capital expenditure programme of US$740 million, covering ongoing terminal expansions, equipment acquisitions, infrastructure upgrades and maintenance.
Among the principal projects are the Phase 3B expansion at Contecon Manzanillo in Mexico and continuing developments at several Philippine terminals, including Manila International Container Terminal, Manila North Harbour, Mindanao Container Terminal and South Luzon Container Terminal.
Other investment projects include ICTSI Rio in Brazil and Matadi Gateway Terminal in the Democratic Republic of Congo.
The group is also progressing additional expansion projects in Honduras, Australia and Ecuador, alongside the next development phase at Contecon Manzanillo.
The investment programme is intended to increase handling capacity and support service improvements across ICTSI’s international operations.
The latest results demonstrate the growing contribution of newly integrated terminals to ICTSI’s financial and operational performance. At the same time, the limited increase in adjusted container throughput and the decline in consolidated EBITDA margin highlight the importance of distinguishing portfolio expansion from underlying operational growth.